Our Core Equity strategies are designed to sit between traditional active and passive approaches — offering access to systematically captured active conviction, while remaining cost‑competitive with other index and factor‑based solutions.
Rethinking how portfolios are built
Finding the right balance between cost and returns is not always easy.
Equity portfolios are expected to do a lot. They need to be diversified, cost-aware and pursue long term growth – while keeping pace with changing market conditions.
Investors approach this in different ways. Some rely on broad market exposure, which keeps costs low but includes everything, regardless of quality. Others use factor-based strategies, which offer a more selective, cost-efficient approach and group stocks based on shared characteristics. And many turn to active managers for more selective, high-conviction ideas, accepting a higher cost in return for that insight.
Four factors are standard. Conviction is not.

Franklin Core Equity Funds are designed with that balance in mind.
They start with established factors – quality, value, sentiment and alternative – that have helped explain market behaviour over time. We then add a fifth element: conviction.
Conviction reflects how strongly fund managers back their ideas. It shows up in how portfolios are built – not just which stocks are held, but how much is invested in each one.
We look at how fund managers allocate capital to identify where those strongest views lie. We then bring that insight together with established factors in a systematic, benchmark-aware approach.
The resulting strategies aim to keep the discipline and consistency investors value, while adding an extra layer of potential alpha drawn from active decision-making.
Adding conviction to a structured approach
Traditional factor approaches are efficient but they do not distinguish between strong and weaker ideas. Conviction adds that dimension by identifying where active managers commit capital with greatest confidence.
By integrating those signals alongside established factors within a disciplined framework, the strategies allow insight to be expressed more clearly – without compromising the structure and predictability expected of core equity allocations.
Understanding the fifth element
Two short articles exploring why conviction matters and how it is identified, extracted and applied.

Why conviction matters in factor investing
A closer look at the role of conviction and why it is not fully captured by traditional approaches.

Capturing conviction: from portfolios to signal
How the strategy extracts conviction from fundamental portfolios and turns it into a usable signal.

Designed for a core role in portfolios
Market exposure plus differentiation
The strategies are designed to stay closely aligned to broad market exposure, while introducing a differentiated source of return.
Franklin Core Equity Funds balance factor exposures with conviction, while maintaining tight control over risk and diversification. The portfolios are constructed to behave as investors would expect from a core allocation, without taking large or unintended risks.
The result is: strategies that fit naturally within a portfolio – familiar in structure, but broader in the sources of return they draw on.
Cost matters in core portfolios
Core allocations are typically held for long periods, which means costs compound over time. Any additional source of return needs to be delivered efficiently.
Long-term cost efficiency matters
Positioned between active and passive
By embedding conviction within a quantitative framework, the strategy avoids the cost structure of fully active management, while retaining a disciplined approach to risk and diversification.
Disciplined conviction without active costs
Management fees vary by fund and share class and currently range from 0.13% to 0.22% for Series F. Explore the fund details below.
Performance
Franklin Core Equity Funds are built to support more consistent, risk-aware outcomes over time. The combination of diversified factor exposures and disciplined portfolio construction is designed to help smooth returns and support long-term goals—without adding unnecessary cost or complexity.
Three Core Equity funds now have a five-year track record for their Series O share class, reflected in the performance shown below. The tabbed chart displays Series O performance for each fund. For key insights and an at-a-glance summary of the funds, see the Franklin Core Equity Funds flyer.
- Franklin U.S. Core Equity Fund
- Franklin International Core Equity Fund
- Franklin Canadian Core Equity Fund
Franklin U.S. Core Equity Fund
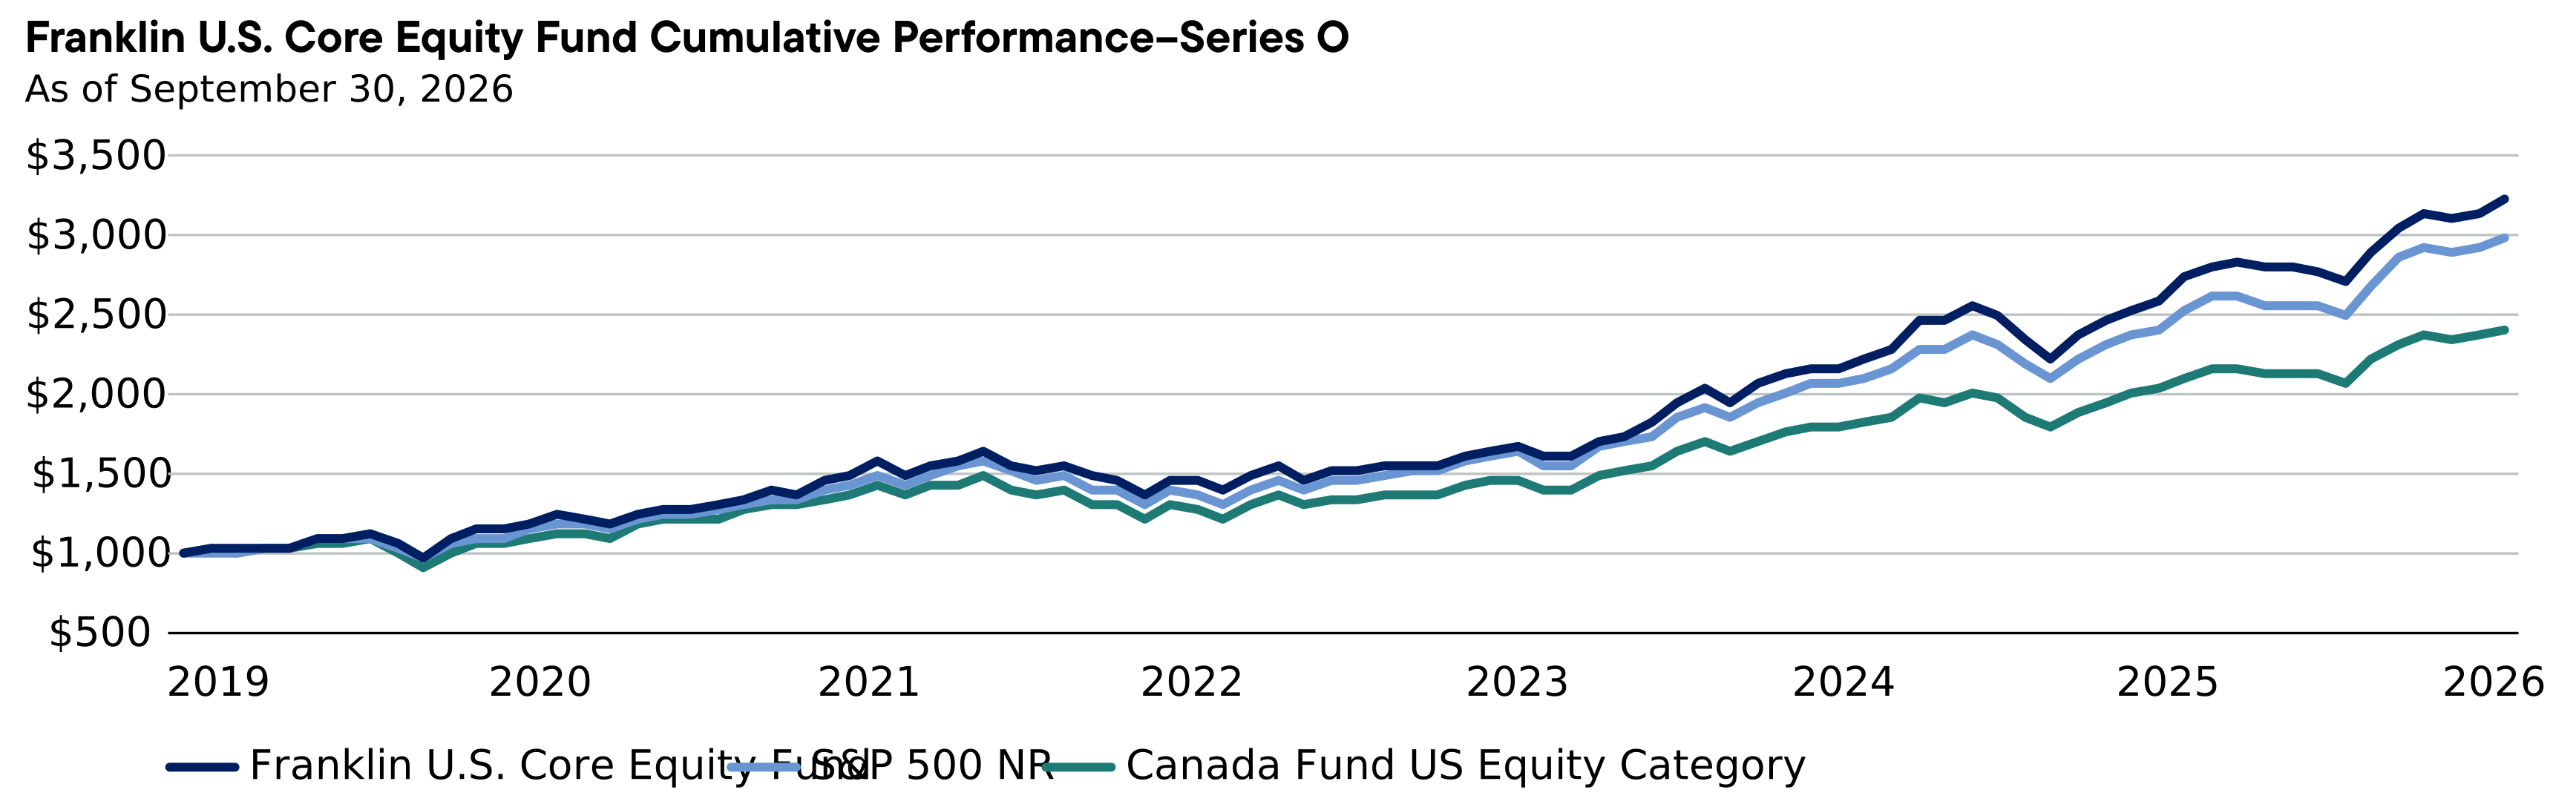
Average Annual Total Returns (%)
As of September 30, 2026
| Inception Date | 1 Yr | 3 Yrs | 5 Yrs | Since Incept | ||
|---|---|---|---|---|---|---|
| Franklin U.S. Core Equity Fund–Series O—(CAD) | 05/06/2019 | 15.16 | 20.53 | 15.16 | 15.48 | |
*Canada Fund U.S. Equity Category (CAD).
Past performance does not guarantee future results. Performance data quoted represents past performance, which does not guarantee future results. Current performance may be lower or higher than the figures shown. Principal value and investment returns will fluctuate, and investors' shares, when redeemed, may be worth more or less than the original cost. For current month-end performance, please visit www.franklintempleton.com
Franklin International Core Equity Fund
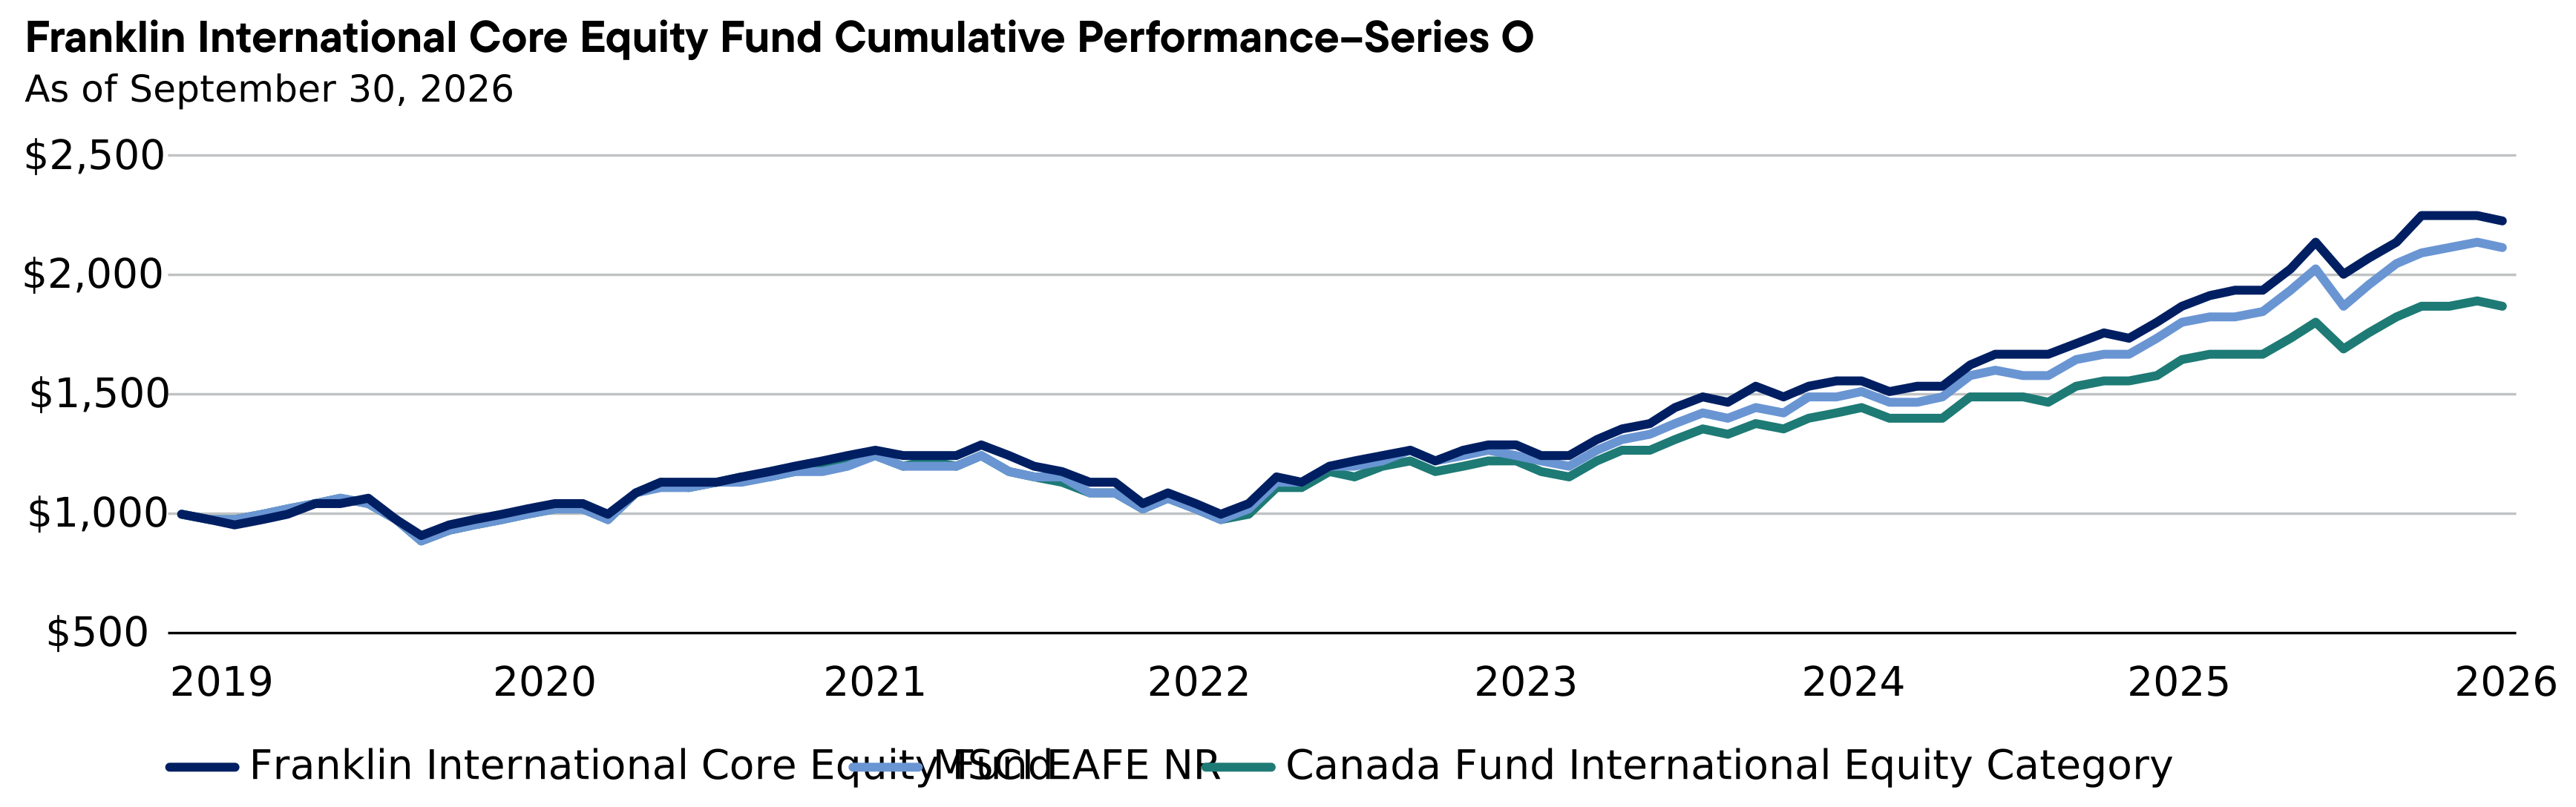
Average Annual Total Returns (%)
As of September 30, 2026
| Inception Date | 1 Yr | 3 Yrs | 5 Yrs | Since Incept | ||
|---|---|---|---|---|---|---|
| Franklin International Core Equity Fund– Series O—(CAD) | 05/06/2019 | 20.15 | 17.20 | 11.50 | 10.37 | |
*Canada Fund International Equity Category (CAD).
Past performance does not guarantee future results. Performance data quoted represents past performance, which does not guarantee future results. Current performance may be lower or higher than the figures shown. Principal value and investment returns will fluctuate, and investors' shares, when redeemed, may be worth more or less than the original cost. For current month-end performance, please visit www.franklintempleton.com
Franklin Canadian Core Equity Fund
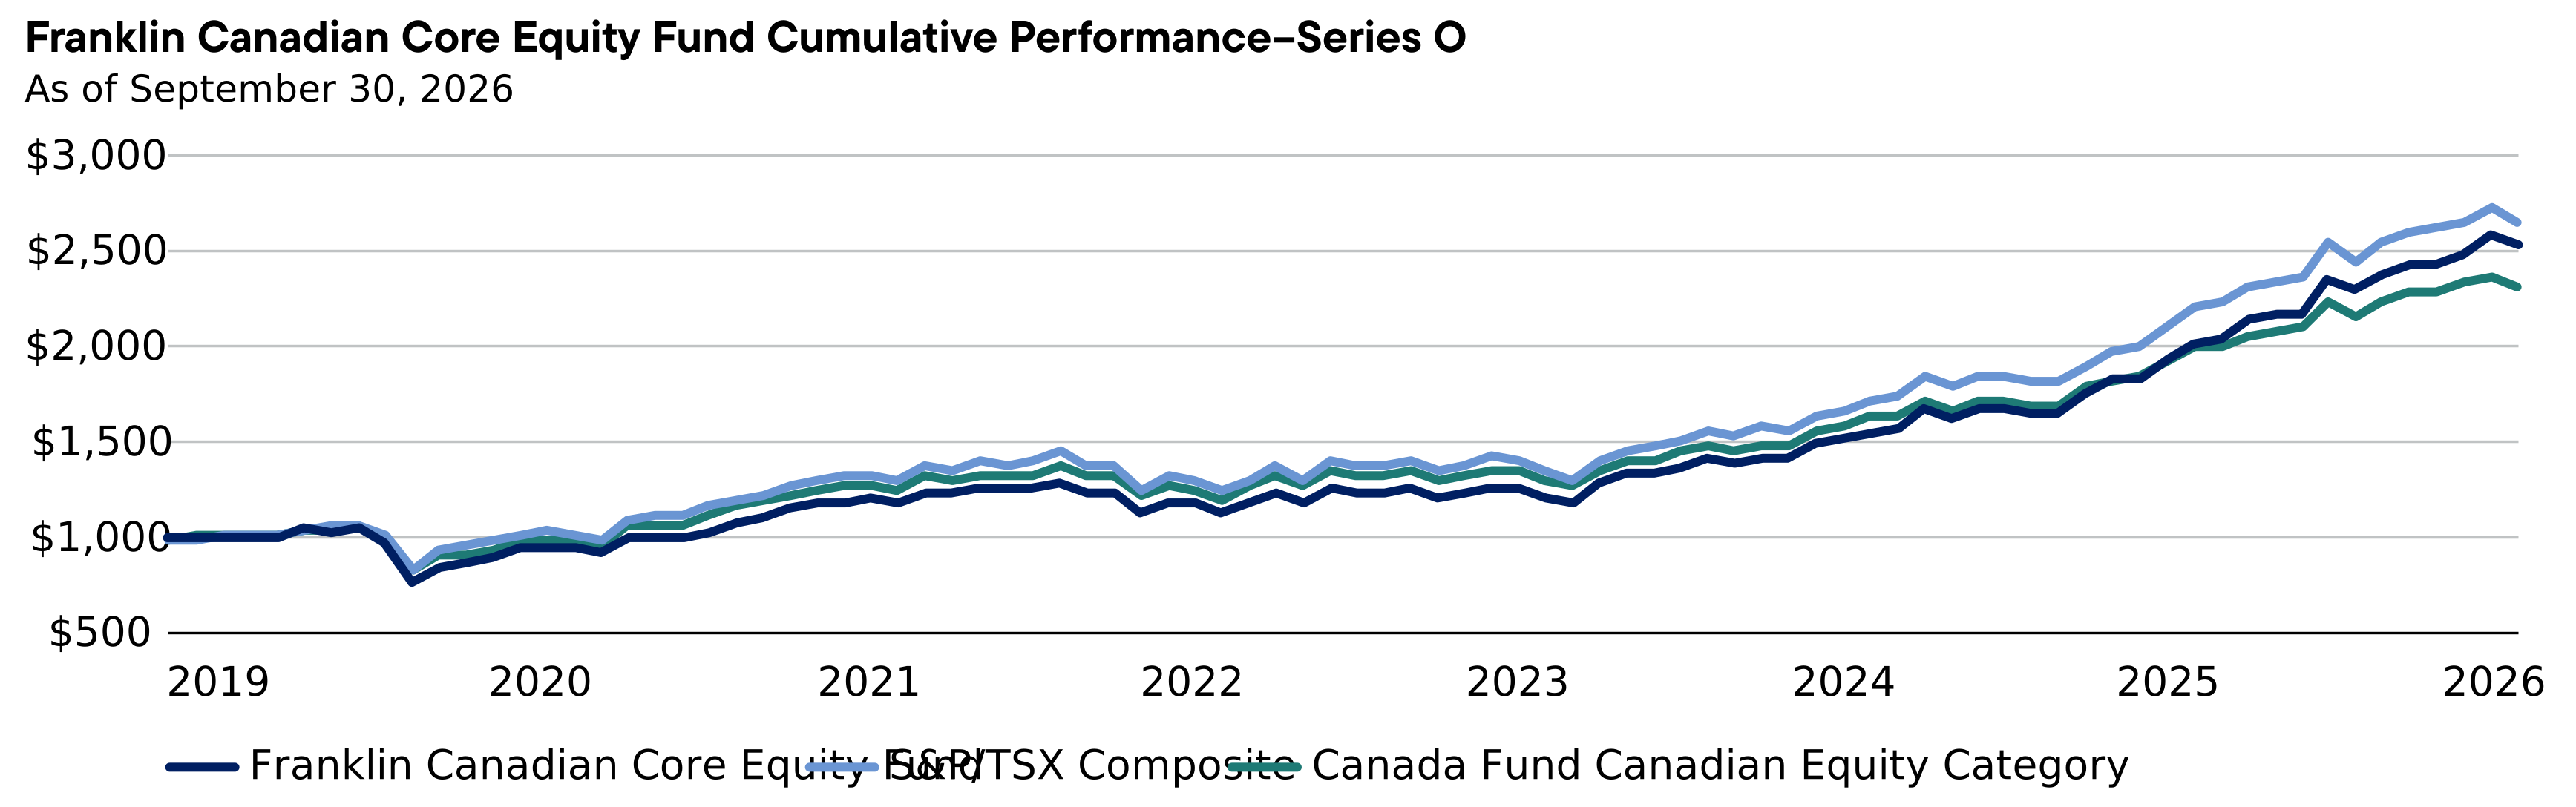
Average Annual Total Returns (%)
As of September 30, 2026
| Inception Date | 1 Yr | 3 Yrs | 5 Yrs | Since Incept | ||
|---|---|---|---|---|---|---|
| Franklin Canadian Core Equity Fund – Series O (CAD) | 05/06/2019 | 38.04 | 22.91 | 16.10 | 12.78 | |
*Canada Fund Canadian Equity Category (CAD).
Past performance does not guarantee future results. Performance data quoted represents past performance, which does not guarantee future results. Current performance may be lower or higher than the figures shown. Principal value and investment returns will fluctuate, and investors' shares, when redeemed, may be worth more or less than the original cost. For current month-end performance, please visit www.franklintempleton.com
Explore the funds
Franklin Canadian
Core Equity Fund
| Series | Mgmt. fee with Waiver* |
Admin. Fee |
|---|---|---|
| ETF | 0.13 % | 0.05 % |
| F | 0.13 % | 0.05 % |
| A | 1.13 % | 0.05 % |
| Fund Details | ||
Franklin U.S.
Core Equity Fund
| Series | Mgmt. fee with Waiver* |
Admin. Fee |
|---|---|---|
| ETF | 0.17 % | 0.05 % |
| F | 0.17 % | 0.05 % |
| A | 1.17 % | 0.05 % |
| Fund Details | ||
Franklin International
Core Equity Fund
| Series | Mgmt. fee with Waiver* |
Admin. Fee |
|---|---|---|
| ETF | 0.22 % | 0.05 % |
| F | 0.22 % | 0.05 % |
| A | 1.22 % | 0.05 % |
| Fund Details | ||
Franklin Global
Core Equity Fund
| Series | Mgmt. fee with Waiver* |
Admin. Fee |
|---|---|---|
| ETF | — | — |
| F | 0.22 % | 0.05 % |
| A | 1.22 % | 0.05 % |
| Fund Details | ||
* The management fee will be partially waived until December 31, 2026.
Data as of September 30, 2026.
Backed by deep expertise
The Franklin Core Equity Funds are managed by Franklin Templeton Investment Solutions (FTIS), a global multi-asset team with decades of experience in quantitative research, portfolio design and systematic equity strategies. The team brings together deep expertise across asset classes, regions and investment styles—supported by a legacy of innovation that dates back to the 1980s, and they’ve been refining their approach ever since.
Today, the team includes over 90 investment professionals across 12 global offices, managing more than CAD$139 billion in assets.

Ready to build a smarter core equity exposure?
Talk to your Franklin Templeton representative to learn how Core Equity Funds can support your portfolio strategies.
FAQ's
The Franklin Core Equity Funds strategy is designed to provide broad equity market exposure, similar to a benchmark, while seeking to deliver incremental outperformance through a systematic investment approach. It aims to balance consistency of returns with modest alpha generation within a controlled risk framework.
Passive strategies aim to replicate an index at low cost, while traditional active strategies take higher-conviction positions that can lead to greater deviation from the benchmark.
Franklin Core Equity Funds sits between the two—maintaining benchmark-like characteristics while introducing diversified, systematic sources of alpha.
Franklin Core Equity Funds are designed to sit at the core of an equity allocation, providing broad market exposure while enhancing return potential.
It can be used alongside passive and high-conviction active strategies to improve overall portfolio efficiency within a defined risk budget.
Franklin offers four Core Equity funds in Canada: Canadian, U.S., International and Global. The Canadian, U.S. and International funds are available as mutual funds and as ETF series listed on the Toronto Stock Exchange (TSX). The Global fund is available as a mutual fund.
The funds are:
- Franklin Canadian Core Equity Fund: ETF series ticker FCRC (TSX). Also available as a mutual fund.
- Franklin U.S. Core Equity Fund: ETF series ticker FCRU (TSX). Also available as a mutual fund.
- Franklin International Core Equity Fund: ETF series ticker FCRI (TSX). Also available as a mutual fund.
- Franklin Global Core Equity Fund: Available as a mutual fund. No ETF series.
Each fund is designed to serve as the core of an investor's equity allocation in its region. Fees, series and ETF details vary by fund, so review each fund's fund facts or ETF facts and the prospectus before investing. The management fee is partially waived until December 31, 2026.
A benchmark-aware approach is constructed to maintain similar risk characteristics to a reference index, with tight control over tracking error. This allows the strategy to function as a core holding, without introducing unintended factor, sector or regional biases.
Factor investing involves targeting specific characteristics—such as quality, value, momentum (sentiment), and others—that have historically been associated with excess returns over time.
These factors are grounded in both academic research and market behaviour, and can provide a systematic and transparent way to access long-term return drivers across equity markets.
The strategy incorporates established factors including quality, value, sentiment and alternative signals, which help explain differences in stock returns. These are combined in a diversified and risk-controlled manner to improve consistency of outcomes across market cycles.
A single-factor strategy focuses on one source of potential return, such as value, quality or momentum. For example, a value strategy may perform well when inexpensive stocks are in favour but struggle when market conditions favour other investment styles.
A multifactor approach combines different sources of potential return, reducing reliance on any one factor. Franklin Core Equity Funds bring together five elements:
- Quality: Companies with strong financial fundamentals, such as high profitability and relatively low debt.
- Value: Stocks trading at attractive valuations relative to earnings or book value.
- Sentiment: Signals such as price momentum and changes in analysts' earnings expectations.
- Alternative: Additional investment signals beyond traditional factor measures.
- Conviction: Insights drawn systematically from the portfolio positioning of Franklin Templeton's fundamental investment managers.
When one factor underperforms, strength in others may help offset some of that weakness. The conviction factor adds a further dimension by incorporating the forward-looking views of experienced stock pickers1.
The trade-off is that a multifactor approach may not capture the full upside when a particular factor is performing strongly. Instead, Franklin Core Equity Funds aim to deliver more consistent, benchmark-aware outcomes across different market environments, rather than relying on the success of any single investment style.
1. Franklin Templeton, Why conviction matters in factor investing.
Conviction captures the strength of active managers’ investment views, as expressed through their portfolio positioning—particularly stock weightings.
By systematically extracting this information, the strategy introduces an additional, differentiated source of return that is not typically captured by traditional factor models.
Combining factor and active investing allows investors to benefit from both systematic, research-driven return drivers and fundamental stock-picking expertise.
Factor investing provides consistency and diversification, while active insights can introduce differentiated sources of return. Integrating the two can create a more balanced and resilient approach to equity investing.
Generating consistent alpha typically requires combining multiple sources of return rather than relying on a single approach.
This can include blending factor exposures, maintaining diversification, controlling unintended risks, and incorporating high-conviction insights from active managers. Approaches that integrate these elements within a disciplined framework may improve the consistency of outcomes over time.
Risk is managed through a disciplined, benchmark-aware construction process, with diversification across factors and tight controls on tracking error.
The strategy also seeks to neutralise uncompensated risks—such as unintended sector, country or style exposures—ensuring that returns are driven primarily by intended sources of alpha.
Not necessarily. Core equity aims to manage unintended risk, rather than be defensive. Franklin Core Equity Funds use a disciplined investment approach designed to control risks that could cause performance to diverge significantly from their benchmarks.
Three elements are particularly important:
- Benchmark-aware risk management: Portfolios are constructed to maintain risk characteristics broadly similar to their benchmarks, limiting unintended sector, country or style exposures.
- Tracking-error controls: Tracking error measures how closely a fund's returns follow its benchmark. Franklin Core Equity Funds seek to maintain relatively low tracking error, helping to limit unintended deviations from benchmark performance.
- Downside capture: This measures how much of a benchmark's decline a fund experiences when markets fall. A ratio below 100% indicates that the fund has declined less than its benchmark. Franklin Core Equity Funds aim to achieve downside capture below 100% over a full market cycle, helping to limit losses relative to the benchmark.
Core equity is not a low-volatility or defensive strategy. Investors remain exposed to equity market movements, including the potential for losses when markets decline. The objective is to manage unintended risks while maintaining the characteristics of a core equity allocation.
Evaluating a core equity fund involves looking beyond returns to assess how effectively it balances outperformance potential with risk and costs.
Five measures can help:
- Active share: Shows how much a fund's holdings differ from its benchmark. A core equity fund should offer meaningful differentiation without excessive concentration.
- Tracking error: Measures how closely returns follow the benchmark. Relatively low tracking error is generally consistent with a benchmark-aware approach
- Information ratio: Measures excess return per unit of tracking error. An information ratio of 0.5 is generally considered good, while 1.0 is exceptional2.
- Fees: Lower costs help preserve the incremental returns that core equity strategies seek to generate.
- Return attribution: Helps establish whether outperformance comes from intended sources, such as stock selection and factor exposures.
For example, a hypothetical fund delivering 0.5% annual excess return with 1% tracking error has an information ratio of 0.5. Another delivering 1% excess return with 4% tracking error has a ratio of just 0.25. The first has generated more excess return per unit of active risk, despite its lower absolute outperformance. The key is assessing whether the returns justify the risks and costs involved.
2. CFA Institute, The Sharpe Ratio and the Information Ratio — information-ratio guidance.